Along with the rapid growth of digital banking, the need for robust fraud detection systems has become increasingly critical. These systems must continuously monitor transactions, recognise unusual behaviour, identify emerging fraud patterns and help banks respond before losses escalate. While rule-based systems remain essential for enforcing established controls, AI-driven analytics can help identify suspicious activity that may not match known patterns. In a modern banking technology environment, both approaches can complement Core Banking Software (CBS) to strengthen fraud monitoring without compromising transaction speed, customer experience or regulatory oversight.
What Is Rule-Based Fraud Detection?
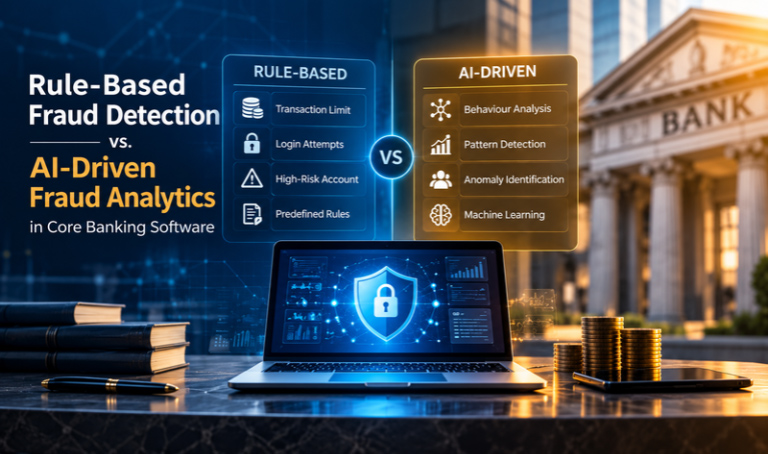
Rule-based fraud detection operates on predefined conditions established by a bank's risk and compliance teams. When a transaction meets a specified condition, the system triggers an alert, blocks the transaction or routes it for further verification, depending on the system's configuration.
For example, a bank may configure rules to flag transactions exceeding a particular amount, multiple failed login attempts, repeated withdrawals within a short period or transfers to a previously identified high-risk account. These rules are relatively straightforward to implement, test and explain. Investigators can usually trace an alert to the specific condition that triggered it.
Within a Core Banking Software environment, transaction and account information can support fraud monitoring at various stages, including fund transfers, withdrawals, loan disbursements and changes to customer information. When integrated with suitable monitoring systems, CBS can contribute to the consistent enforcement of established risk thresholds and banking controls.
A fundamental limitation of rule-based fraud detection is that it primarily identifies activities covered by its configured rules. If criminals change their tactics, for example, by splitting a large transfer into several smaller transactions or spreading transactions across multiple accounts, they may avoid triggering existing rules. Individual transactions may appear legitimate even when the overall pattern of activity is suspicious.
To address evolving fraud techniques, banks must regularly review and update their rules. However, adding too many rules can generate excessive false alerts, making it harder for investigation teams to identify genuine fraud. It can also result in legitimate transactions being flagged unnecessarily, causing delays and inconvenience to customers.
How AI Transforms Fraud Detection
AI-driven fraud analytics uses machine learning and behavioural analysis to examine transaction patterns and identify suspicious activity. Unlike rule-based systems, which rely on predefined conditions, AI models can identify deviations from normal behaviour and uncover relationships between seemingly unrelated accounts or transactions.
For example, a customer who usually makes small domestic transfers during business hours suddenly starts transferring money to several new beneficiaries, followed by quick withdrawals from related accounts. Each transaction may fall within the bank's permitted limits, but the sudden change in behaviour and the pattern of linked transactions could indicate fraud. An AI model can flag the activity as high-risk for further investigation.
AI-driven analytics can help banks detect fraud across multiple channels, including mobile banking, internet banking and card transactions, provided relevant data is available and appropriately integrated. This can be particularly useful when fraudsters spread their activities across different channels to avoid detection.
The Bank for International Settlements has examined the role of machine learning and data-driven techniques in identifying patterns relevant to financial crime and improving the analysis of payment-related data. Such research highlights the potential of advanced analytics to complement conventional monitoring approaches.
Advantages of AI-Driven Fraud Detection in Banking
1. Real-Time Detection and Response
Fraud prevention can become more effective when risk assessment takes place before a suspicious transaction is completed, wherever the transaction flow permits it. When Core Banking Software is integrated with suitable real-time monitoring and risk management systems, it can support data exchange and transaction monitoring workflows. Depending on the connected systems and their capabilities, these workflows may facilitate risk alerts, additional authentication or transaction holds.
2. A More Complete View of Risk
Core Banking Software maintains important information about accounts, balances, customer relationships and transaction histories. When this information is appropriately integrated with data from digital channels, payment systems and fraud case-management platforms, it can contribute to a more comprehensive view of potential risks. Analysing information across these systems can help banks identify patterns that might remain unnoticed when individual systems are monitored separately.
3. Better Prioritisation of Alerts
Fraud investigation teams often need to review a large volume of alerts. AI-based risk scoring can help rank cases according to their estimated likelihood and potential impact, allowing investigators to focus on higher-risk activities. The effectiveness of this approach depends on model quality, data accuracy and appropriate calibration.
4. Stronger Early-Warning Capabilities
Fraud analytics can extend beyond individual transactions to identify linked accounts, repeated patterns and potential risks in lending operations. In India, the Reserve Bank of India's 2024 Master Directions on Fraud Risk Management strengthened the framework for fraud governance, early warning signals and red-flagging of accounts. These requirements underline the importance of structured monitoring, timely identification of potential risks and appropriate follow-up.
Key Differences Between Rule-Based and AI-Led Fraud Detection
- Detection approach: Rule-based systems check transactions against predefined conditions, while AI models analyse data to identify suspicious patterns and anomalies.
- Emerging fraud: Rule-based systems generally require updated rules to address new techniques, while AI models can help identify previously unseen anomalies when supported by suitable data and effective model design.
- Behavioural analysis: Rules focus on specified conditions, whereas AI can identify deviations from a customer's usual transaction patterns.
- Cross-channel detection: AI can help identify connections across accounts and banking channels when relevant data is available and integrated.
- Explainability: Rule-based alerts are generally easier to trace to a specific condition. AI-generated risk scores may require additional explanation to support investigation and decision-making.
- Maintenance: Rules require regular review, while AI models need data-quality checks, performance monitoring and periodic validation.
-
Alert management: AI can help prioritise cases by risk, but its effectiveness depends on model quality, calibration and ongoing monitoring.
A Hybrid Approach
Research published by IEEE in 2024 explores approaches to fraud detection and related analytical methods. Research in this area highlights the importance of balancing detection performance with computational efficiency and interpretability, although the findings depend on the specific methods and applications studied.
Rule-based detection and AI analytics serve different purposes, and a hybrid approach can combine their respective strengths. Rules are effective for enforcing established controls, while AI can help uncover complex patterns and prioritise suspicious activity. The appropriate balance depends on a bank's risk profile, operational requirements, available data and regulatory obligations.
For banks, effective fraud detection depends on how well monitoring and risk controls work alongside core banking operations. By combining predictable controls with analytical capabilities within a well-governed banking technology environment, financial institutions can strengthen fraud prevention, improve investigation efficiency and protect customer trust. The integration of these capabilities with Core Banking Software should be planned according to the bank's requirements and the functionality of the systems involved.
Nelito’s Core Banking Software for Modern Banking Operations
As banks continue to modernise their technology infrastructure, a reliable Core Banking Software solution remains essential for supporting day-to-day banking operations. Nelito Systems provides Core Banking Software designed to support banks' operational requirements and evolving business needs. Banks can complement their core banking systems with specialised fraud monitoring and risk management solutions to strengthen their broader technology ecosystem and address emerging security challenges.
References
Comments :